Normal? Really?
I hear the same thing almost every week from buyers in Fort Lauderdale, Wilton Manors, and Oakland Park: "We're going to wait until rates drop back down." When I ask what they're waiting for, most people say 5%, some say lower. I get why. Rates in the high 5s and low 6s feel steep compared to what we saw a few years ago. But if you look at where mortgage rates have actually sat over the past fifty plus years, today's rates aren't high at all. They're right in the normal range, and they have been for most of American history.
What Does Fifty Years of Mortgage Rate History Actually Show?
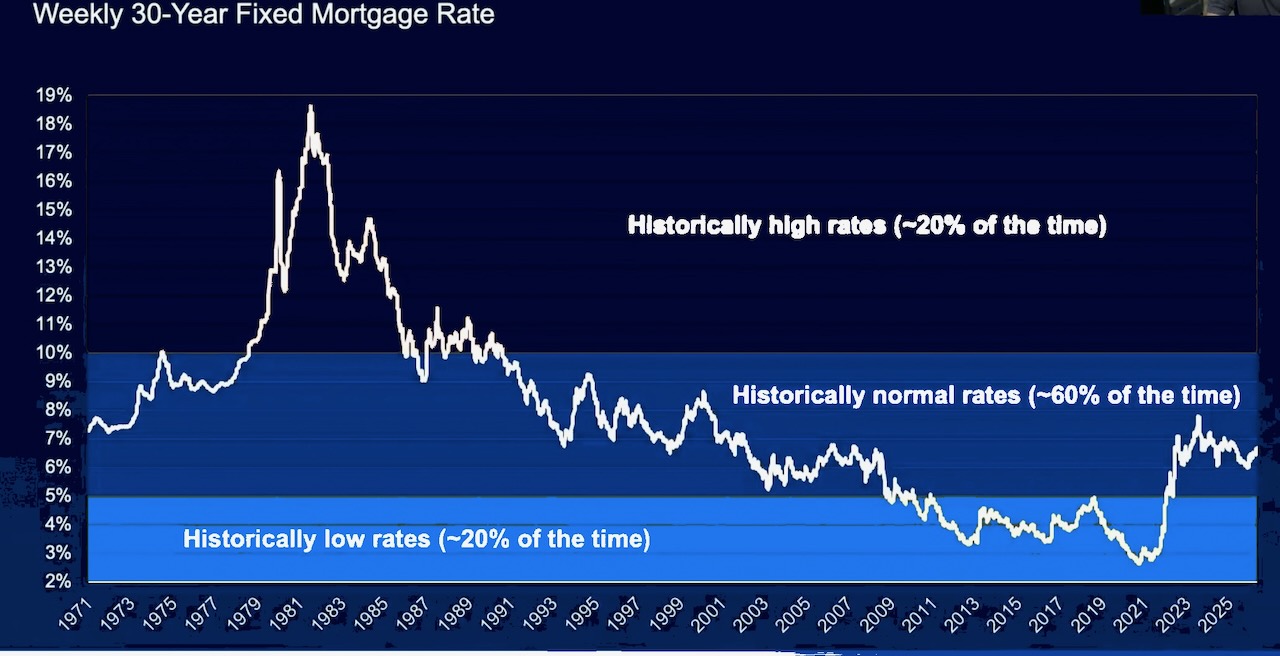
50 Year History of Weekly Fixed Rate Mortgage Rates
Freddie Mac has tracked the weekly 30-year fixed mortgage rate since 1971, and that data tells a clear story once you break it into three bands.
Rates above 10% only happened about 20% of the time, mostly during the late 1970s and 1980s, when the 30-year fixed rate spiked above 18%. Rates below 5% also only happened about 20% of the time, and almost all of that stretch came after the 2008 financial crisis, especially from 2011 through 2021. The middle band, rates between 5% and 10%, is where the market has spent roughly 60% of the time since 1971. That's the normal range, not the exception.
So when someone tells me they're waiting for 3% or 4% rates to come back, I remind them that those rates were the product of a global financial crisis and, later, a pandemic. They weren't the standard. The 5% to 7% range we're in now is much closer to how mortgage rates have behaved for most of the last five decades.
Where Do Today's Rates Fall in That History?
As of late summer 2026, the weekly average for a 30-year fixed mortgage sits in the mid 6% range. That places us solidly inside the "historically normal" band, not the high band, and not far above the lower edge of normal either.
For buyers who bought their first home in the early 2010s or refinanced during the pandemic, this can feel jarring. But for buyers who purchased homes in the 1990s or 2000s, a rate in the 6s is nothing new. It's worth remembering that plenty of families in Fort Lauderdale, Wilton Manors, and Oakland Park bought their homes at these same rates or higher and built real equity along the way.
Why Do 4 in 10 Buyers Expect Rates Below 5% This Year?
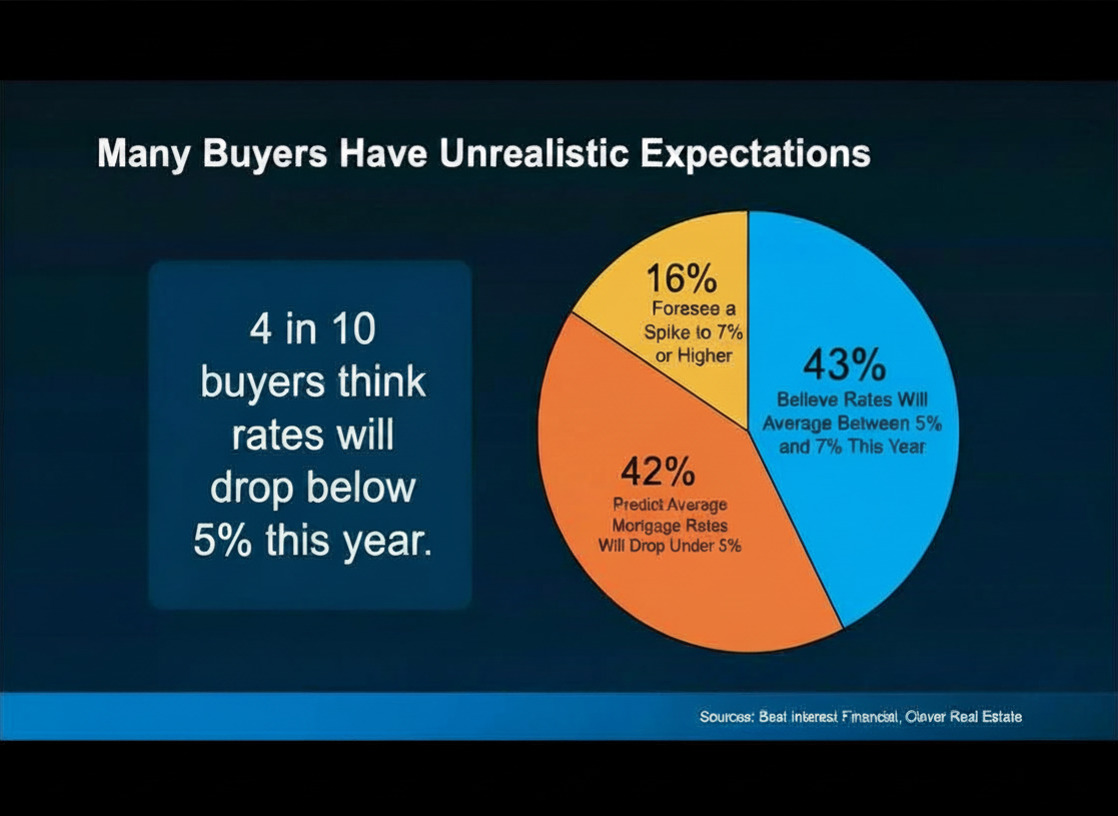
Buyer Mortgage Rate Expectations
Here's where it gets interesting. A recent survey from Best Interest Financial and Clever Real Estate found that a big share of buyers have expectations that don't line up with where rates actually are or where most forecasts point.
According to that survey, 42% of buyers predict average mortgage rates will drop under 5% this year, and another 16% think rates could spike to 7% or higher. Only 43% expect rates to average somewhere in the realistic 5% to 7% range, which is where most housing economists actually expect rates to land.
That means roughly 4 in 10 buyers in the market right now are holding out for a number that isn't supported by current data or most forecasts. If you're one of the buyers waiting on the sidelines for rates to fall under 5%, it helps to know you're not basing that on where the market has been trending. You may be waiting on a number that simply reflects an unusually low period rather than a realistic target.
What This Means If You're Buying in Fort Lauderdale, Wilton Manors, or Oakland Park
I'm not telling anyone rates don't matter. They absolutely affect your monthly payment and how much home you can afford. What I am saying is that waiting for a specific rate that may not come, while home prices and rents keep moving in our local market, can cost you more than the rate itself would.
A few things I tell my buyers:
You can always refinance later if rates drop. You can't go back and buy today's price at yesterday's level once inventory tightens or a home you liked gets sold.
Local inventory in Wilton Manors and Oakland Park tends to move quickly on well priced homes, regardless of what national rate headlines say. Waiting on a rate prediction can mean missing a home that fits your life right now.
A loan officer can walk you through rate buydowns, ARMs, and other options that soften the impact of a 6% to 7% rate on your monthly payment, so you're not simply stuck choosing between "wait" or "pay full price."
If you're trying to figure out what a home actually costs you at today's rates versus waiting for a rate that may or may not show up, that's a conversation worth having before you decide to sit out the market.
Ready to Talk Through Your Numbers?
I've been a Florida licensed REALTOR® since 2003 and I've watched rates move through several cycles in this exact market. If you want to figure out what makes sense for your situation in Fort Lauderdale, Wilton Manors, or Oakland Park, reach out and let's run the numbers together.
Start Your Home Search or Get in Touch to talk about your next move in South Florida.
Frequently Asked Questions
Are today's mortgage rates high compared to history? No. Data going back to 1971 shows mortgage rates have spent about 60% of the time between 5% and 10%. Today's rates, in the mid 6% range, fall inside that normal band.
How often have mortgage rates been below 5%? Rates below 5% have occurred about 20% of the time historically, and most of that period happened after the 2008 financial crisis through 2021. It was an unusually low stretch, not the long-term norm.
Do most buyers expect mortgage rates to drop below 5% this year? A recent survey found 42% of buyers expect rates to fall below 5% this year, but most housing economists expect rates to average in the 5% to 7% range instead.
Should I wait to buy a home in Fort Lauderdale until rates drop? That depends on your personal finances and goals, but waiting on a rate that history and current forecasts don't support can mean missing out on homes in Wilton Manors, Oakland Park, and Fort Lauderdale that fit your needs today. A local agent and lender can help you compare the real cost of waiting versus buying now.
Check out this article next